Compare TS70 Car Insurance Quotes
- Cover After A TS70
- Quotes Can Improve Over Time
- Cover Levels To Choose From
- Compare TS70 Quotes

TS70 Conviction: Points, Ban And Years On Your Licence
Yes, you can usually get car insurance with a TS70. Insurers set their own rules on traffic sign offences, so prices and choice may vary, and specialist brokers can search for insurers that consider them. A TS70 is an undefined failure to comply with a traffic direction sign, carries 3 points and stays on your licence for 4 years from the offence date, or from conviction if the court bans you.
- Points 3 From a fixed penalty, or from a court if it doesn't ban you.
- On your licence 4 years From the offence date, or from conviction if you're banned.
- Ban Possible A court can ban you instead of giving points.
- Insurers may see it 4 years Any time while it's on your record.
GOV.UK doesn't say which sign a TS70 covers. For failing to comply with a traffic sign, a fixed penalty is £100 and 3 points, and in court the maximum fine is £1,000.
What Is A TS70 Motoring Conviction?
TS70 is the endorsement code for an undefined failure to comply with a traffic direction sign. GOV.UK's endorsement code list gives it 3 penalty points, and it stays on your driving record for 4 years from the date of the offence, or from conviction if the court bans you.
Unlike TS10 to TS60, the code's wording doesn't name a particular sign or direction, and GOV.UK gives no more detail about it. TS10 is traffic lights, TS20 double white lines, TS30 a 'stop' sign, TS40 a police officer's or traffic warden's direction, TS50 other traffic signs and TS60 a school crossing patrol's sign.
TS70 Penalties: What To Check
The Road Traffic Act's traffic signs offence covers a driver who fails to comply with a sign of the prescribed type that's lawfully placed on or near a road. The penalties schedule gives it a maximum fine of £1,000 and 3 points, with a possible ban, and it can't lead to prison. The Sentencing Council's list of penalty notices gives £100 and 3 points for failing to comply with a traffic sign. GOV.UK doesn't say which law a TS70 is recorded under, so check your fixed penalty notice or court papers for the offence and the penalty you were given.
Those 3 points can matter more than the fine. GOV.UK says your licence is cancelled if you get 6 or more points within 2 years of passing your test, so two 3-point codes in that time would be enough. The Highway Code says points you got before passing count too. The points also count towards a ban for 3 years, and the Sentencing Council says reaching 12 or more points means the court must normally ban you for at least 6 months, or longer if you had an earlier ban of 56 days or more in the 3 years before the offence.
Checking What Your TS70 Was For
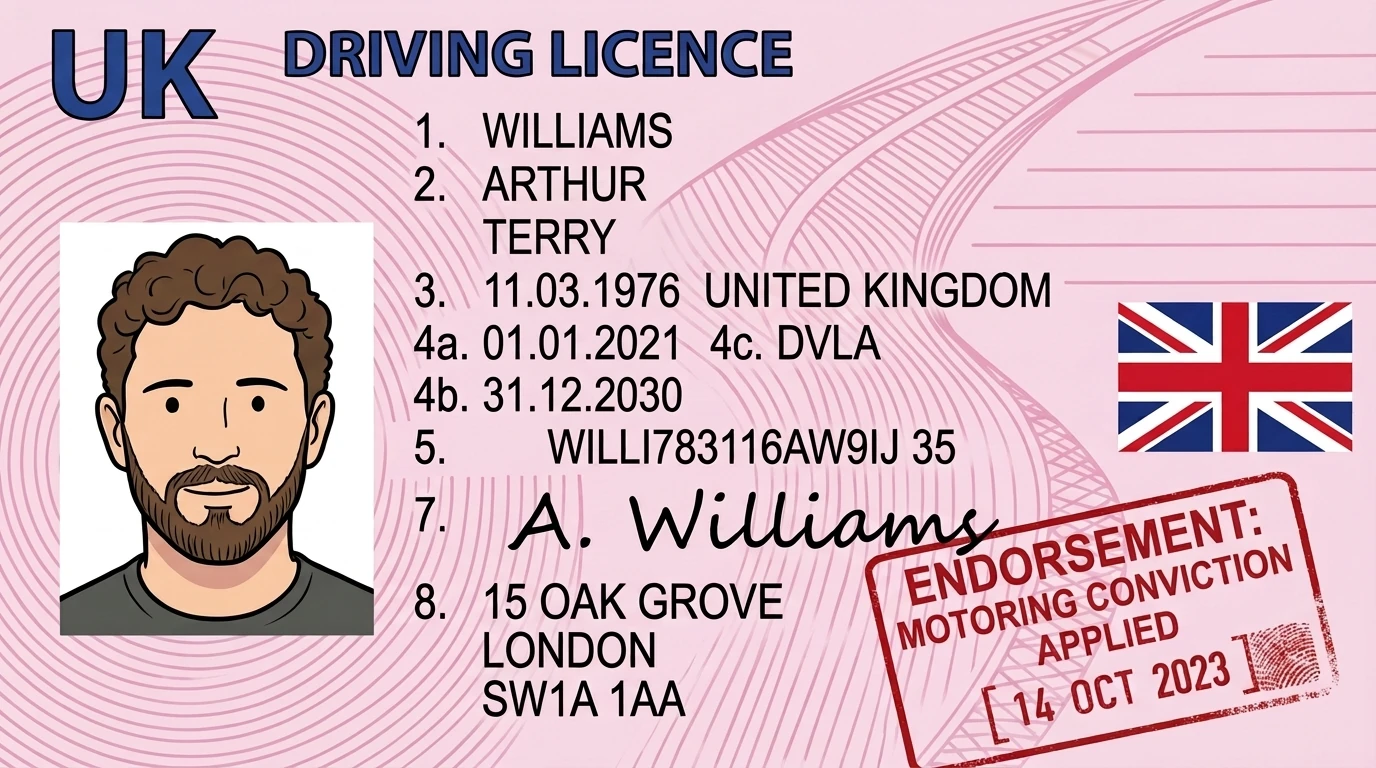
Because the code doesn't name the sign, your own paperwork is the place to look: the fixed penalty notice, or the court's letter if it went to court. GOV.UK's view your driving licence service lets you check your penalty points or disqualifications, so you can give insurers the same details your record shows.
Give Insurers The Code As It's Recorded
Give the code as TS70, with the dates and points your record shows, even if you know which sign it was. If an insurer asks what the offence was, describe it as your paperwork does. Swapping in a code that seems a better fit can leave the insurer with details that don't match your record.
Traffic Signs That Give Orders
The Highway Code's rule on traffic signs and signals says you must obey all traffic light signals and traffic signs giving orders, including temporary signs. Its guide to traffic signs says signs with red circles are mostly prohibitive, and signs with blue circles but no red border mostly give a positive instruction. Direction signs, by contrast, are mostly rectangular.
Sources: GOV.UK's endorsement code list and view your driving licence service, and the Highway Code on GOV.UK, checked 15 October 2026. Endorsement codes and processes in Northern Ireland are different.
This information is based on our understanding of current law and insurance practice at the time of writing. Rules, penalties and rehabilitation periods can change and may apply differently depending on individual circumstances.
Other Traffic Sign And Totting-Up Codes
| Code | Offence | Points | On licence |
|---|---|---|---|
| TS10 | Failing to comply with traffic light signals | 3 | 4 years |
| TS20 | Failing to comply with double white lines | 3 | 4 years |
| TS30 | Failing to comply with a 'stop' sign | 3 | 4 years |
| TS40 | Failing to comply with direction of a constable/warden | 3 | 4 years |
| TS50 | Failing to comply with a traffic sign (excluding 'stop' signs, traffic lights or double white lines) | 3 | 4 years |
| TS60 | Failing to comply with a school crossing patrol sign | 3 | 4 years |
| TT99 | Disqualification under the totting-up procedure | None | 4 years |
Can You Get Car Insurance After A TS70 Conviction?
Yes. Specialist brokers can look for insurers that consider a TS70, though prices may be higher while it's recent. Each insurer sets its own rules, but most ask about convictions from the last 5 years, and our guide on how insurers assess a conviction covers the general rules.
Getting Back On The Road After A TS70 Ban
A TS70 doesn't automatically mean a ban, but a court can disqualify you. If it does, don't drive until the ban has ended. You can compare quotes before then: MIB says to buy your insurance ahead of the date you need the cover to start. GOV.UK says that if you're banned for 56 days or more, you must apply for a new licence before driving again, and the court will tell you if you also have to retake your test. For a shorter ban, you don't need a new licence, but you can't drive until it has ended.
Do You Have To Tell Your Insurer About A TS70?
Yes, whenever the insurer's questions cover it, until it's spent. That can include a TS70 from a fixed penalty, if the question asks about endorsements, points or fixed penalties, and it can be after the points stop counting and after it leaves your record. Give the code, dates and points exactly as your paperwork or licence record shows. If you get it during a policy, MoneyHelper says you don't have to declare it until you renew, unless your policy says you must.
What Cover Can You Get With A TS70 Conviction?
Comprehensive cover may still be available after a TS70. Some insurers may offer only third party, fire and theft or third party cover, or ask for a higher excess or a black box.
Driving a van or riding a motorbike with a TS70? It's on your driving record whatever you drive, so those insurers may ask about it too. See van insurance after a TS70 or motorbike cover with a TS70.
Please note that policy features, benefits, terms and conditions vary among insurance providers, so always check the policy wording.
Cover Tip: Give the code as TS70, exactly as your record shows it, on every quote. MIB says wrong or out-of-date details can leave you uninsured without realising.
Telling Your Insurer About A TS70 Conviction
Insurers may be able to find out about a TS70 for the whole time it's on your record, and you'll need to answer their questions accurately until it's spent, which for an adult is later. For timings, read how long a driving conviction needs declaring.
- Answer The Conviction Questions Accurately - Under the Consumer Insurance (Disclosure and Representations) Act 2012, what an insurer can do about a wrong answer depends on whether it was careless, or deliberate or reckless. MoneyHelper says an insurer can reject a claim if it has reason to believe you didn't take reasonable care to answer its questions truthfully and accurately.
- Insurers May Be Able To See It For 4 Years - GOV.UK says insurers may be able to find out about an endorsement any time during a 4-year endorsement. A TS70's points only count towards a ban for the first 3 years, but most insurers' questions go back 5 years, and points that have stopped counting still need declaring if the insurer's question covers them.
- Check What Each Question Covers - A TS70 from a fixed penalty is still an endorsement with 3 points on your record. Insurers word their questions differently: some ask about convictions, others about endorsements, penalty points or fixed penalties. Answer each question as it's worded, and if you're not sure whether it covers a fixed penalty, ask the insurer or broker before you buy.
- What Can Happen If Details Are Wrong - The Financial Ombudsman says an insurer might charge more, restrict the policy, settle a claim only in part, or cancel the policy as if it never existed, which means any ongoing claim will be declined.
- When A TS70 Is Spent - For an adult in England and Wales, a TS70 from court is spent 5 years from conviction (2.5 years if you were under 18). Government guidance says one from a fixed penalty also becomes spent after 5 years, counted from when the penalty was imposed. A ban that runs past that keeps it unspent until the ban ends. Most insurers ask about the last 5 years, and a 2026 Financial Ombudsman decision found an endorsement inside those 5 years still had to be declared, even though its points had expired. Once it's spent, MoneyHelper says you don't need to declare it, even if you're asked.
How Does A TS70 Conviction Affect Your Insurance Price?
There's no single price for car insurance after a TS70. MoneyHelper says cover might be more expensive with an unspent conviction. These are the things that can shape a quote.
| Key Factor | Impact on your price |
|---|---|
| Your points or a ban | A TS70 carries 3 points, whether it came from a fixed penalty or a court. A ban instead of points may suggest a more serious case to an insurer and may narrow the choice of cover. |
| Other points and codes | A TS70 on top of other endorsements may raise the price further. 12 or more points within 3 years normally means a ban. |
| How long ago it happened | A recent conviction may be priced higher. Don't assume the price falls at every renewal, as each insurer sets its own rules. |
| The car you choose | Its value, power and any modifications all count. MIB says unmodified cars are generally cheaper to insure. |
| Mileage, use and parking | Give a realistic mileage, the right type of use and where the car is kept. MIB says wrong or out-of-date details can leave you uninsured without realising. |
The quotes you get will depend on your own details.
Price Insight: Use the code, points and dates exactly as your record shows them on every TS70 quote, so the prices you compare are based on the same details. For an adult it's spent after 5 years.
How Can You Help Reduce Insurance Costs After A TS70 Conviction?
While it's unspent, a TS70 stays in a quote when insurers ask about it, but the details around it are yours to change.
-
Ask About A Black Box Policy
Ask whether a black box policy is offered with a TS70. MIB says telematics policies can reward safe driving with lower premiums over time.
-
Check The Insurance Group First
Check the group before you buy a car. MIB says lower-group cars are typically smaller, cheaper to repair and more affordable to insure.
-
Keep The Excess Affordable
Raise the voluntary excess only to a level you could pay if you claimed. MIB says a higher excess can reduce the premium.
-
Quote Before You Need Cover
MIB says quotes are likely to be lowest 20 to 26 days before your renewal is due, and starting early leaves time to compare.
Expert View On A TS70 Conviction
A TS70 can be confusing because the code itself doesn't say what happened. That doesn't change how insurers treat it: it's 3 points on your record, and they may ask about it.
A common mix-up is treating three different dates as one. GOV.UK's guide to how long endorsements stay says the points count towards a ban for the first 3 years and the endorsement stays on your record for 4. For an adult it isn't spent until 5 years.
My rule of thumb: find the paperwork that came with your TS70 and keep it with your insurance documents, so the code, dates and points you give every insurer match your record.
About this page


This page was written by Susan Difford, Co-Founder and Personal Lines Expert, and reviewed by Ian Beevis, Co-Founder and Insurance Expert. Updated 30 October 2026.
TS70 Conviction Insurance Questions
What Does 'undefined' Mean On A TS70?
It means the code's wording doesn't name a particular sign. GOV.UK lists TS70 as an undefined failure to comply with a traffic direction sign, with 3 points for 4 years, and gives no more detail. Check your fixed penalty notice or court papers for the details of the offence.
Do I Give Insurers The TS70 Code Or Describe The Sign?
Give the code as it appears on your record, TS70, with its dates and points. If an insurer asks what the offence was, describe it as your paperwork does.
Do I Have To Declare A TS70 After 3 Years?
Yes, if an insurer's questions cover it and it isn't spent yet. The points stop counting towards a ban after 3 years. The TS70 leaves your licence 4 years after the offence, or after conviction if you're banned, and insurers may be able to find out about it in that time. In England and Wales it's usually spent 5 years after conviction (2 years 6 months if you were under 18), or when any ban ends if that's later. Once it's spent, MoneyHelper says you don't need to declare it, even if you're asked.
As of October 2026. Source: GOV.UK: Penalty points (endorsements), legislation.gov.uk: Rehabilitation of Offenders Act 1974, section 5, MoneyHelper: Getting insurance with a criminal conviction.
Is A TS70 A Criminal Record?
It depends on how it was dealt with. From a court, a TS70 is a conviction for a criminal offence. GOV.UK says a fixed penalty won't appear on your criminal record unless a court gives you a conviction because of one, though government guidance says its endorsement is treated as a conviction when working out when it's spent. MoneyHelper says a criminal conviction can be anything from a prison sentence to a fine. If a form asks about criminal convictions, see insurance with a criminal record.
Can A TS70 Affect A New Driver's Licence?
Yes. GOV.UK says your licence is cancelled if you get 6 or more points within 2 years of passing your test. A TS70 carries 3, so a second 3-point code in that time would be enough, and the Highway Code says points you got before passing count too. You'd then have to apply for a new provisional licence and pass both the theory and practical tests again.
What Are The Penalties For A TS70?
A traffic sign or direction offence that carries points, like a TS70, can be dealt with by a fixed penalty of £100 and 3 points. In court, the maximum fine is £1,000 with 3 points, or the court can ban you instead. These offences don't carry a prison sentence.
As of October 2026. Source: legislation.gov.uk: Fixed Penalty Order 2000, Schedule 1, GOV.UK: Endorsement codes and penalty points, legislation.gov.uk: Road Traffic Offenders Act 1988, Schedule 2, legislation.gov.uk: Sentencing Act 2020, section 122.
How Much Does A TS70 Affect Car Insurance?
There's no set amount, as each insurer prices a TS70 its own way. As at October 2026, Go.Compare's median annual premium for drivers with a traffic direction and signs conviction was £521 (sales 1 March to 31 May 2026). Its median for drivers with no convictions was £381 (comprehensive cover, 1 January to 30 June 2026). Your own price may be higher or lower.
As of October 2026. Source: Go.Compare convicted driver insurance data (updated 23 September 2026).
Are The Rules On Traffic Signs Changing?
Not yet. The government's motoring offences consultation (7 January to 11 May 2026) didn't include traffic sign offences among its proposals, and no response had been published by 29 October 2026, so the current rules still apply.
As of October 2026. Source: GOV.UK: Proposed changes to penalties for motoring offences.
Who Can Cover You With A TS70?
Specialist convicted driver brokers search for insurers that consider traffic sign offences, and you may be able to get quotes from some of them via the Clean Green Cars site. Mainstream comparison sites and insurers you approach direct may also quote, though some may not for a TS70, and prices may vary a lot. Each broker and insurer has its own range, so prices may differ and it may be worth comparing more than one route.
What Happens After I Submit My Details?
Clean Green Cars introduces you to specialist brokers who consider TS70 convictions. They contact you with quotes based on your details, and you're under no obligation to accept any quote.
What To Have Ready Before Comparing Quotes With A TS70 Conviction
Have these to hand before you get quotes.
- Your TS70 offence date, and the conviction or fixed penalty date
- Your fixed penalty notice or court papers, in case an insurer asks what the offence was
- Any other points on your record and their dates, and any ban dates
- The car's registration and where it's kept overnight
- Your annual mileage, type of use and claims history
Get Quotes For A TS70 Conviction
Sources For TS70 Conviction Facts
- GOV.UK: endorsement codes and penalty points - TS70 points and years on your record (checked 15 Oct 2026).
- GOV.UK: how long endorsements stay on your record - when the 4 years start, the 3-year valid period and when insurers may see it (checked 15 Oct 2026).
- GOV.UK: view your driving licence - checking your penalty points or disqualifications (checked 15 Oct 2026).
- Road Traffic Act 1988, section 36 - the traffic signs offence (checked 15 Oct 2026).
- Road Traffic Offenders Act 1988, Schedule 2 - the maximum fine, 3 points and possible ban (checked 15 Oct 2026).
- Sentencing Council: out of court disposals - the £100 and 3-point penalty notice for a traffic sign offence (checked 15 Oct 2026).
- The Highway Code: traffic signs - signs giving orders and direction signs (checked 15 Oct 2026).
- GOV.UK: rehabilitation periods - when endorsements and bans are spent (checked 15 Oct 2026).
- GOV.UK: Rehabilitation of Offenders Act guidance - fixed penalty endorsements treated as convictions (checked 15 Oct 2026).
- GOV.UK: driving convictions and your criminal record - fixed penalties and criminal records (checked 15 Oct 2026).
- GOV.UK: driving disqualifications - applying for a new licence after a ban (checked 15 Oct 2026).
- MoneyHelper: insurance with a criminal conviction - unspent convictions, specialist policies and the spent rule (checked 15 Oct 2026).
- MoneyHelper: if your insurance claim is rejected - answering the application questions with reasonable care (checked 15 Oct 2026).
- Financial Ombudsman: misrepresentation - what an insurer can do if an answer is wrong (checked 15 Oct 2026).