
Why Compare Iveco Horsebox Insurance?
Daily Or Eurocargo Changes The Quote
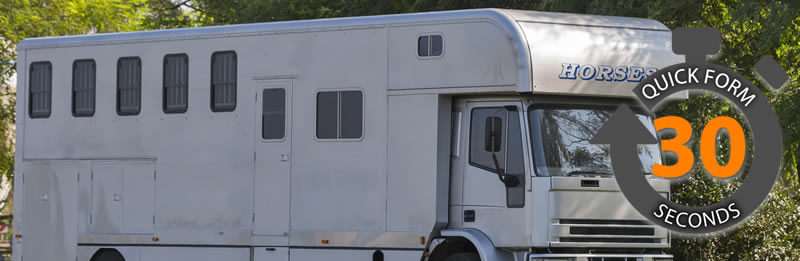
A 3.5t Daily, a 7.2t Daily and a 7.5t Eurocargo can each be rated differently. Comparing providers side by side shows who quotes well for your chassis and plated weight.
Uprates Need To Be On Record
A Daily uprated from 6.5t should be quoted at its current plated weight. Comparing on accurate details helps avoid problems if you need to claim.
Agreed Value Protects The Build
Coachbuilt bodies from firms like Oakley or Freddie Gover can be worth more than a market valuation shows. Clean Green Cars introduces you to UK providers of horsebox cover, so you can compare agreed value options on your Iveco in one form.
Iveco Horsebox Insurance At A Glance
- Iveco Specifics - Iveco horseboxes come on two chassis. The Daily covers boxes from 3.5t to 7.2t and the Eurocargo starts at 7.5t, so one badge can mean a car-licence box or a medium lorry.
- Daily For Light And Mid-Weight Boxes - Iveco lists the Daily chassis cab from 3.5t to 7.2t. Oakley, Freddie Gover, Trevett & Smith, Equi-Trek and PRB all build 7.2t Daily boxes, and Regent builds 3.5t boxes on Iveco among other makes.
- Eurocargo For 7.5t Builds - the Eurocargo range starts at 7,500kg with the 75E. Oakley mounts its 7.5t Supreme on an ML75E21, and PRB lists 7.5t Iveco stock.
- Ford Iveco And Cargo On Older Boxes - in the 1990s the Eurocargo was sold in the UK as the Cargo under the Iveco Ford partnership, so a used box may say Ford Iveco or 75E15. Quote it exactly as the V5C describes it.
- Plated Weight Beats The Model Name - many Daily chassis started at 6.5t and were later uprated to 7t or 7.2t. The licence, the annual test and the price all follow the MAM on the V5C, not the name on the cab.
- Compare Quotes - see UK insurance providers quoting for your Iveco's chassis, plated weight and use. The horsebox insurance guide covers the rules for every make.
Is Insurance Required For An Iveco Horsebox?
Yes. Any Iveco horsebox used on a road or other public place needs at least third party insurance, from a 3.5t Daily to a 7.5t Eurocargo. GOV.UK says uninsured driving can bring a £300 fixed penalty and 6 penalty points, and the vehicle can be seized.
- Public Road Use Needs Insurance - third party cover is the legal minimum, and the rule doesn't change with the chassis or the weight on the plate.
- SORN Off-Road Storage - a Daily or Eurocargo declared SORN and kept off the road doesn't legally need insurance. Laid-up cover for fire and theft still protects a box that stands idle through the winter.
- V5C Must Match The Box - after a conversion or an uprate, the V5C must be updated so the body type and weight are right. Quote on exactly what the V5C now shows.
- Provider Conditions Matter - some providers may set security or storage conditions on a newer 7.2t or 7.5t Iveco. Read them before you buy, as missing one could affect a theft claim.
Iveco Horsebox Licence Requirements
DEFRA Welfare In Transit Essentials
Getting the licence right puts the Iveco on the road. The welfare-in-transport rules then decide whether a journey needs authorisation. Leisure trips with your own horse sit outside them, while paid moves and professional riding sit inside. Here's what to know first.
Type 1 Or Type 2 Transporter Authorisation
Moving horses more than 65km (about 40 miles) for an economic activity, such as paid transport or professional riding, needs APHA transporter authorisation. Type 1 is for journeys up to 8 hours and type 2 for anything longer, and journeys over 8 hours need vehicle approval too.
Journey Logs For Long Trips Abroad
Journey logs only apply to journeys over 8 hours to a country outside the UK with unregistered horses. Section 1 must reach APHA (the Animal and Plant Health Agency) at least 2 working days before departure, and the completed log goes back within one month of unloading.
Registered Horse Exemption
A horse counts as registered if it belongs to an EU-recognised studbook or a national branch of an international racing or competition body. Registered horses skip journey logs and the journey-time, rest and feeding limits, but transporter authorisation and an animal transport certificate still apply in scope.
Cover Levels Explained
Third party only on a coachbuilt 7.2t Daily or 7.5t Eurocargo leaves the box itself uninsured, so one fire or theft could mean a total loss. Here's what each level typically includes.
| Feature | Comprehensive | Third Party, Fire & Theft | Third Party Only |
|---|---|---|---|
| Liability to third parties (legal minimum) | Yes | Yes | Yes |
| Fire and theft of the Iveco horsebox | Yes | Yes | No |
| Accidental damage to chassis cab and conversion bodywork | Yes | No | No |
| Tack and personal effects in transit | Often included up to a limit | Provider-dependent | No |
| Agreed value on a coachbuilt Daily or Eurocargo | Often available | Provider-dependent | No |
| Custodial liability (horses in your care that you don't own) | Often add-on | Add-on | No |
| Public liability for livery or eventing use | Often included or add-on | Provider-dependent | No |
| European Union driving cover | Yes (period-limited) | Yes (period-limited) | Yes (period-limited) |
| Breakdown with recovery matched to the plated weight | Often add-on | Add-on | Add-on |
| Horse-onward-care or livery during breakdown | Often add-on | Provider-dependent | No |
| Personal accident benefit for driver and passenger | Typically yes | Provider-dependent | No |
Please note that policy features, benefits, terms and conditions vary among insurance providers, so always check the policy wording.
Cover Tip: On most Iveco horseboxes, the value is in the coachbuilt body, not the Daily or Eurocargo cab. Partitions, ramps, groom areas and living fit-outs tend to drive the repair bills, and comprehensive is usually the only level that pays for accidental damage to them. Agreed value, tack in transit and custodial liability (cover for horses in your care that you don't own) are usually separate extras, so check each one on the quote.
What May Not Be Covered
A plated weight that doesn't match the V5C, or paid lifts on a leisure policy, can leave an Iveco horsebox claim in trouble. Here's what a standard Iveco policy typically doesn't cover.
Standard Exclusions
- Out-Of-Date V5C Details - If the Iveco's body type or weight has changed and the V5C hasn't been updated, the vehicle on your policy may not match the one on the road. DVLA must be told after a conversion, and the insurer needs the same details.
- Undeclared Coachbuilder Or Conversion - Added living, an extra stall, a new ramp, a lithium battery or self-build work that hasn't been declared may invalidate cover. Name the coachbuilder on the form, whether that's Oakley, Freddie Gover, Trevett & Smith or a one-off build.
- Driving Outside Licence Entitlement - Driving a 7.2t Daily or 7.5t Eurocargo on a category B licence alone, without C1 or pre-1997 entitlement, is outside your licence and may invalidate the policy. The van-style Daily cab doesn't change that.
- Undeclared Hire And Reward - Taking other people's horses for payment, a fuel contribution or prize money while rated for social, domestic and pleasure use is typically excluded. Paid transport needs a commercial horsebox policy, and above 3,500kg usually an operator licence too.
Important Limitations
- Uprates Without Telling The Insurer - Uprating a Daily from 6.5t to 7t or 7.2t, or taking a 3.5t Daily into the C1 band, without telling the provider may invalidate cover. The plated weight on the V5C, the chassis plate and the quote should all match.
- Storage Or Security Breach - Providers sometimes require a tracker, an immobiliser or locked storage on newer Daily and Eurocargo boxes. Breaking a stated condition may invalidate a theft or vandalism claim, even when everything else on the policy is in order.
Extras Worth Considering
Recovering a 3.5t Daily and a 7.5t Eurocargo are different jobs, and the wrong breakdown cover could leave horses at the roadside for hours. These extras may be worth adding to an Iveco policy.
Taking a Daily or Eurocargo box to continental shows? Extended European cover at comprehensive level may be worth adding instead of the basic minimum. Horses travelling to the EU also need an export health certificate.
A 3.5t Daily may suit heavy-duty van recovery, but a 7.2t Daily or 7.5t Eurocargo usually needs HGV-capable recovery. Horse onward-care or temporary livery may keep a breakdown from becoming a welfare problem.
On a coachbuilt Daily or Eurocargo from Oakley, Freddie Gover, Trevett & Smith, Equi-Trek or PRB, agreed value sets the payout at the start. That avoids relying on a market valuation that may miss what the conversion is worth.
Lockers full of saddles, rugs and show kit, plus horses you carry for friends or clients, may sit above the limits of a base policy. A tack-in-transit and custodial extension brings the limits closer to what the Iveco really carries.
What Affects The Cost?
The chassis, the plated weight, the value of the build and how the box is used all move an Iveco horsebox quote. Here are the factors that shape the price.
| Key Factor | Impact on your price |
|---|---|
| Declared vehicle value | A new 7.2t Daily or 7.5t Eurocargo build and a 1990s Ford Iveco box can be worlds apart in value. Quotes usually scale with the declared value of the whole vehicle, body included. |
| Daily or Eurocargo chassis | A Daily and a Eurocargo of similar age may price differently because of weight, value and repair costs. Quote the exact chassis code, such as 70C21 or ML75E21, as the V5C shows it. |
| Maximum Authorised Mass (MAM) | Iveco boxes sit at 3.5t, at 6.5t to 7.2t or at 7.5t. Premiums tend to rise with the plated weight, and an uprated Daily should be rated at its current figure, not its original one. |
| Use type | Social, domestic and pleasure use usually costs least. Business equestrian use such as livery or teaching sits in the middle, and paid client transport costs most on an Iveco horsebox. |
| Driver age and licence history | Older drivers with a long clean licence and horsebox experience usually pay less. A 3.5t Daily can be driven on a car licence, but younger drivers may still pay more, and C1 is needed above 3,500kg. |
| Claims and conviction history | Fault claims in the last five years, on any motor policy, usually push the price up. Recent motoring convictions, even from car cover, can raise an Iveco quote as well. |
| Overnight storage | A locked yard or CCTV-covered compound usually prices lowest, a driveway or barn sits between, and street parking often prices highest for an Iveco box. |
| Annual mileage | Leisure horseboxes usually do far fewer miles than a family car. Give a realistic figure for the Daily or Eurocargo, based on your actual season, rather than a car-style default. |
| Home postcode | Quieter rural postcodes usually price below higher-theft towns and cities. Local theft, flood and storm risk feeds into an Iveco horsebox quote the same way it does for a car. |
| Security devices fitted | An approved alarm, immobiliser, tracker or wheel clamp may help lower the quote. Some providers ask for approved security on newer or agreed-value Daily and Eurocargo boxes. |
Each Iveco quote depends on your own details.
Price Insight: Iveco is unusual because one badge spans car-licence and C1 boxes, from a 3.5t Daily to a 7.2t Daily and a 7.5t Eurocargo. Quotes tend to follow the plated weight, the declared value and the use rather than the Iveco name. A 3.5t box that a car-licence driver can take may draw quotes from a wider choice of providers than a 7.5t lorry.
Ways To Help Reduce Your Premium
Let an Iveco horsebox policy renew without a fresh comparison and the price can creep up year on year. Here are practical ways to help bring it down.
Quote The Current Plated Weight
Read the MAM off the V5C and chassis plate before you quote. Many Daily boxes have been uprated from 6.5t, so the figure in an old advert or brochure may be out of date.
Keep The V5c Up To Date
Tell DVLA after any conversion, uprate or major re-fit. Quoting on details that match the V5C means the provider rates the Iveco you actually drive, not the one it used to be.
Store It Securely
Declare a locked yard, gated barn or CCTV-covered compound if that's where the box really lives. Secure storage tends to make a real difference on a newer 7.2t Daily or 7.5t Eurocargo.
Fit Approved Security
Add a Thatcham-approved alarm, immobiliser or tracker. It may help lower the quote, and some providers require approved security on higher-value Iveco boxes before offering agreed value.
Declare Limited Mileage Where Honest
Work out your miles from last season's shows, lessons and vet visits. Where a provider offers a limited mileage discount, an honest low figure may bring the price down.
Pay Annually If You Can Afford It
Pay the full year upfront if you can. Monthly payments usually carry interest (the APR, the cost of borrowing), which adds to the total you pay for the Iveco policy.
Saving Tip: On an Iveco, getting the plated weight right comes first. An uprated Daily quoted at its old weight is mis-rated from the start, and that can cause trouble if you claim. After that, honest mileage, secure storage and an approved tracker tend to move the quote most. A box that only comes out for the show season rarely needs a car-style mileage figure.
How To Compare Quotes
It takes a few minutes to compare Iveco horsebox insurance from UK insurance providers. Get started above.
Share Your Details
Enter the chassis (Daily or Eurocargo, plus a code such as 70C21), the year, the coachbuilder, the plated weight, the value and your postcode. It only takes a few minutes.
Confirm Body Classification
Check the V5C body type and weight are up to date, then declare any uprate, added living, lithium battery, solar panels or interior re-fit since the box was built.
Compare Cover Levels
Set third party, fire and theft and comprehensive side by side. Then read the tack, custodial liability and agreed value terms on each quote for your Iveco.
Weigh Add-Ons
Choose European cover, breakdown matched to the plated weight and agreed value, based on what the box is worth and whether anyone else's horses travel in it.
Set Inception Date
Choose when cover starts. Once you've paid, the provider issues the certificate and the Iveco goes on the Motor Insurance Database (MID).
What Our Expert Says
Iveco is the badge where the licence question catches people out. A Daily cab looks like a big van, but the Daily horseboxes from builders such as Oakley, Freddie Gover and Trevett & Smith are 6.5t to 7.2t, so the driver needs C1 just as they would on a 7.5t Eurocargo.
The detail to check is the plate. Trevett & Smith say their Daily chassis started at 6.5t and were uprated to 7t, with the newest at 7.2t. Two boxes that look the same can carry different weights, so take the figure from the V5C and chassis plate, not from the advert or the model name.
Older boxes add one more wrinkle. A 1990s Eurocargo may be badged Ford Iveco or Cargo, with a code such as 75E15 on the paperwork. Providers may well quote these, but describe the vehicle exactly as the V5C does and declare any re-fit since it was built.
Insurance Expert & Co-founder of Clean Green Cars
Common Questions
Can I Drive A 7.2t Iveco Daily Horsebox On A Car Licence?
Not on a car licence alone. Category B stops at 3,500kg, and a 7.2t Daily sits in the C1 band of 3,500kg to 7,500kg. Drivers who passed their car test before 1 January 1997 usually have C1 already. Anyone else needs to add C1, which means a theory test and two practical tests.
Does Uprating An Iveco Daily Affect My Insurance?
Yes. An uprate changes the plated weight, and the weight on your quote should match the V5C and the chassis plate. GOV.UK says you must update the V5C when you change the weight of a large vehicle. Taking a 3.5t Daily above 3,500kg also means the driver needs C1 and the box needs the HGV annual test.
Is A 7.2t Daily Treated Differently From A 7.5t Eurocargo?
Not for the licence or the test. Both sit in the C1 band and both take the HGV annual test every year. Quotes may still differ, because the two chassis can differ in value, payload and repair costs. Freddie Gover points to lower diesel and running costs on the Daily than on a traditional 7.5 ton horsebox.
Can I Insure An Older Ford Iveco Or Cargo Horsebox?
Usually, yes. The Eurocargo reached UK roads in 1991 badged as the New Cargo under the Iveco Ford partnership, which ended in 2003, so some used boxes carry that name. Describe the model and code, such as 75E15, exactly as the V5C shows it, and declare the age of the body and any re-fit.
What's Custodial Liability On A Horsebox Policy?
Custodial liability covers your legal liability for horses on board that you don't own. On an Iveco that takes a friend's horse to a show, a livery client's horse to the vet or a pupil's horse to a clinic, it may be the cover that responds if something goes wrong. It's usually an add-on, so check before you carry anyone else's horse.
Does An Iveco Horsebox Need HGV-Capable Breakdown Cover?
It depends on the weight. A 7.2t Daily or 7.5t Eurocargo usually needs HGV-capable recovery, as standard car-style recovery can't lift it. A 3.5t Daily may suit heavy-duty van recovery. Horse onward-care is what looks after the horses as well as the vehicle, whichever Iveco you drive.
Do I Need APHA Transporter Authorisation For My Iveco Horsebox?
Only for journeys linked to an economic activity. Moving horses more than 65km (about 40 miles) for payment, as a livery or as a professional rider needs type 1 authorisation for journeys up to 8 hours, or type 2 beyond that. Taking your own horse to a show purely for leisure is outside the rules.
What Happens After I Submit My Details?
Clean Green Cars introduces you to UK insurance providers or regulated brokers offering horsebox cover. The quotes you see reflect the Iveco chassis, plated weight, use and storage you enter. Compare the cover, price and add-ons, then pick the policy that suits how you use your Daily or Eurocargo.
Search & Compare Quotes From UK Iveco Horsebox Insurance Providers
Useful Resources
- GOV.UK - Driving Licence Categories - the official table of licence categories, showing where a 3.5t Daily, a 7.2t Daily and a 7.5t Eurocargo each fall.
- GOV.UK - Change Vehicle Details On A V5C - how to update the body type after a conversion, or the plated weight after an uprate.
- DVSA - Transporting Horses In Horseboxes And Trailers - DVSA's horsebox guidance on licences, tachographs, operator licences and when prize money makes use commercial.
- GOV.UK - HGV Annual Test - the yearly test for horseboxes over 3,500kg, which includes uprated Daily boxes as well as the Eurocargo.
- GOV.UK / APHA - Transporting Animals In Great Britain - when you need type 1 or type 2 transporter authorisation, a certificate of competence or vehicle approval.