
Safety And Legal Duties At The Scene
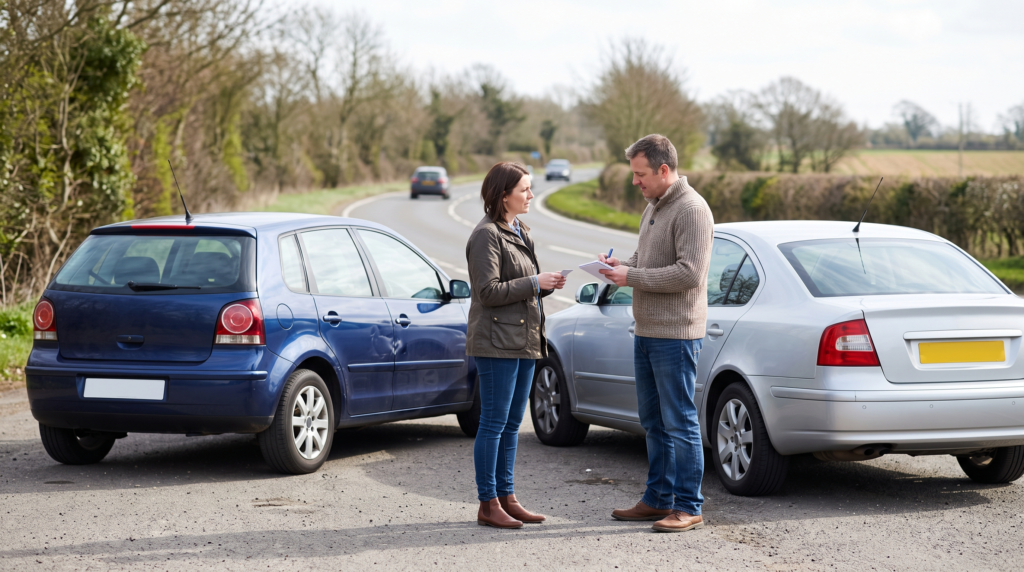
Stop, make the scene safe and seek medical help where needed. Exchange names, addresses and registration details with someone who has reasonable grounds to request them, plus owner details if relevant.
If required details are not exchanged, report the accident to police within 24 hours. GOV.UK also says police should be told when the other driver is uninsured.
Record Facts Without Confronting The Other Driver
Photograph positions, damage and the wider road only when safe. Save dashcam footage and witness contacts.
Note the registration, vehicle description, direction of travel and what was said. Do not pursue a driver who leaves or try to prove insurance status through confrontation.
Give police and insurers observations rather than a final accusation.
Tell Your Insurer Even If Cover Is Unclear
Notify your insurer promptly under the policy terms. Give the police reference and all available evidence.
Comprehensive cover or an uninsured-driver promise may provide a route, subject to wording. Ask about excess, repairs, replacement transport and no claims discount without assuming costs will be recovered.
| Claim Route | When It May Apply | What To Do |
|---|---|---|
| Own insurer | Depends on policy cover | Notify promptly and ask about excess |
| MIB uninsured-driver route | Other driver identified but uninsured | Check current MIB eligibility |
| MIB untraced-driver route | Driver or vehicle not traced | Police and evidence records are important |
| Police | Reporting and possible offences | Keep incident reference |
When The Motor Insurers' Bureau May Be Relevant
The MIB handles eligible claims involving uninsured or untraced drivers under its agreements. Eligibility, evidence and deductions depend on the route and circumstances.
Use the MIB's official claim guidance and current form. It is not a guaranteed alternative payment whenever another driver lacks insurance.
Insurer Route And MIB Route Compared
The best starting route depends on your own cover, whether the other vehicle is identified and what loss occurred. Avoid running inconsistent claims.
Tell each organisation about the other route and follow instructions about repairs or evidence. This table helps frame questions rather than predict an award.
Injury, Repairs And Uninsured Losses
Keep medical records, repair estimates, recovery charges and evidence of other losses. Do not exaggerate or discard damaged items before guidance.
Personal injury and property damage can follow different evidence requirements. Independent legal advice may be appropriate for serious injury or disputed liability, but this guide does not determine legal entitlement.
Keep The Claim File Coherent
Store police, insurer and MIB references together with photographs, statements and invoices. Write a short timeline while events are fresh.
Pass on new evidence and correct mistakes. If a complaint concerns the insurer's handling, use its formal complaint process and check Financial Ombudsman eligibility after a final response or applicable waiting period.
What To Do Over The Next Few Days
Check Who Is Handling Each Loss
Confirm whether your insurer or the MIB is dealing with repairs, injury and other costs. Tell each one about the other route so requests do not conflict.
Follow The Route You Were Given
Reply to requests from your insurer or the MIB within the stated timescale. Ask which evidence is still needed if progress appears to stop.
For future protection, compare car insurance on the cover, excess and uninsured-driver benefits that matter to you.
Claim Detail Priority Chart
This chart shows the details most useful to prepare before making a car insurance claim.
Prepare facts and evidence first. Let the insurer decide how the policy applies.
FAQs
Can I claim if the other driver is uninsured?
You may have a route through your insurer or the MIB, subject to cover, eligibility and evidence.
Should I call the police?
Report the incident where the law or circumstances require it, including injury, failure to exchange details or suspected offences.
Will I lose my no claims bonus?
That depends on your policy and whether costs are recovered. Ask the insurer.
What if the uninsured driver leaves?
Record what you safely can, report the incident and contact your insurer. An MIB route may be relevant.
What evidence should I keep?
Keep photographs, witness details, dashcam files, repair records and all reference numbers.